For underwriters
Write better risks at the right price.
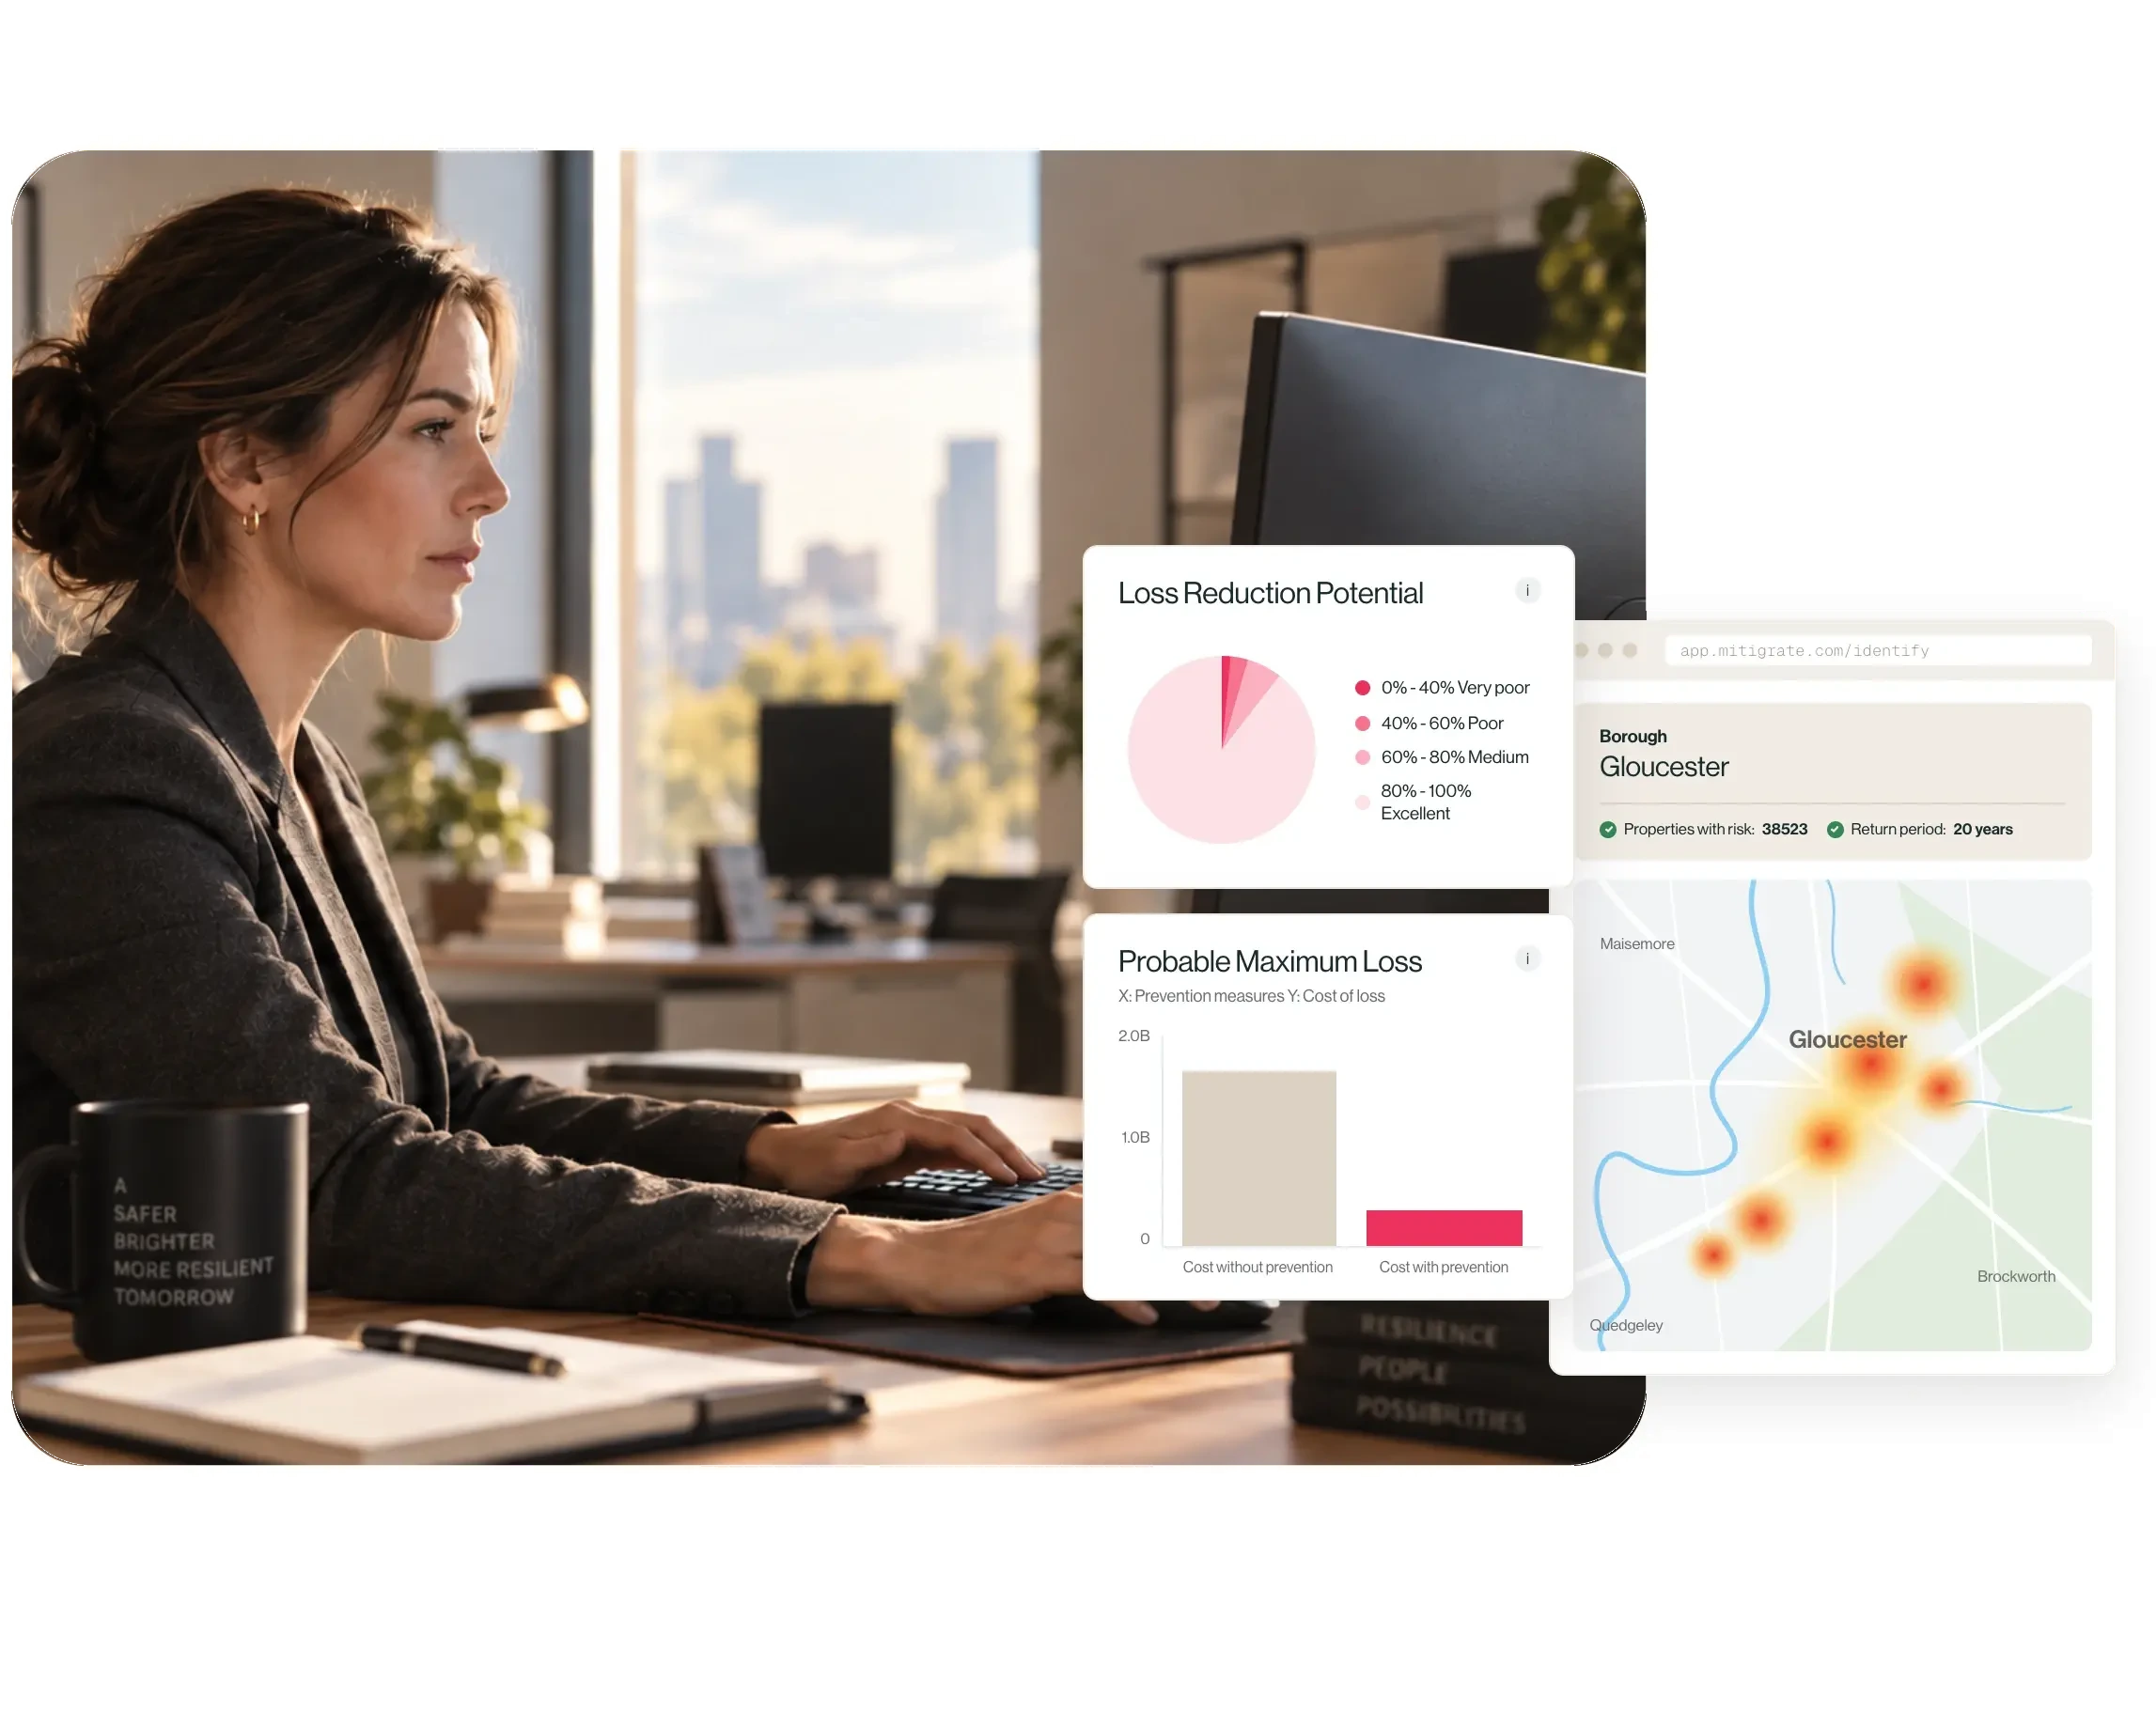
Mitigrate shows you which properties to protect, reprice, or decline based on their prevention potential, helping you select and price risk more accurately.
Trusted by industry leaders

Why Mitigrate
Knowing the flood risk is only half the picture.
Hazard models show where flood risk exists and estimate potential losses. Mitigrate adds the missing piece for underwriters: what can be done to reduce that risk, and how much difference it could make.
01
Make better risk selections
Understand both flood exposure and prevention potential to decide which risks to write, reprice, survey or decline.
02
Assess more properties at scale
Bring property-level assessment across large portfolios without relying on physical surveys for every risk.
03
Turn prevention into an underwriting action
Identify the measures that can reduce physical risk, their cost and expected impact on losses.
04
Build a stronger portfolio
Prioritise the risks where prevention can make the greatest difference and improve portfolio composition over time.
In practice
Make better decisions with a clearer picture of the risk.
01
Focus underwriting where it matters most
Screen the portfolio to identify where prevention can make the biggest difference.
Priority properties
Ranked top loss drivers

Identify the properties driving disproportionate flood losses
Prioritise which risks to write, reprice, survey or decline
02
Understand how each risk can be improved
Assess the property with and without prevention measures before making the underwriting decision.
Current risk
Recommended measures
Expected risk after prevention
See which measures could reduce the risk, their cost and expected impact
Use the results to support pricing, deductibles and coverage decisions
03
Bring verified prevention back into underwriting
Know whether the recommended measures have actually been implemented.
Measure recommended
Implemented ✓
Verified ✓
Updated risk assessment
Verify prevention measures at property level
Use the evidence at renewal or when re-underwriting after a claim
For underwriting teams
Turn prevention into better underwriting decisions
Screen the portfolio to steer underwriting strategy, then use property-level evidence to assess, price and negotiate each risk based on its prevention potential.
01
Steer the portfolio
Identify where prevention can make the biggest difference and use it to inform which risks to write, reprice or decline.
02
Assess risk more accurately
Understand how prevention measures could change the risk at each property — before making the underwriting decision.
03
Improve pricing and terms
Use the expected impact and cost of prevention measures to support decisions on pricing, deductibles and coverage.
04
Reassess risk with evidence
Verify that prevention measures are in place and use that information at renewal or when re-underwriting after a claim.
Trusted by insurers acting on flood risk at scale.
“
We see great potential in this solution. Over time, we can save several billions of Norwegian kroner in damage costs, and we do not doubt it will be profitable. As a minimum, the need for price increases forced by increasingly intense weather will be reduced.
Geir Holmgren
CEO, Gjensidige

“
Mitigrate is transforming flood risk assessment with its cutting-edge software platform that provides property insurers with actionable recommendations to prevent flood damages.
Rosie Denée
Head of Innovation, Commercial Education & Engagement, Lloyd’s

>50%
Of achievable loss reduction sits in the top 5–15% of properties
1:20 – 1:100
Loss modelled before and after mitigation
40+
Prevention measures assessed per property
50M+
Buildings covered in the Nordics and the UK
FAQ
Flood prevention and underwriting
How can flood prevention improve underwriting decisions?
Flood prevention adds another dimension to risk assessment: how much of the risk can actually be reduced. This helps underwriters make more informed decisions about which properties to write, reprice, survey or decline, and what terms may be appropriate.
How can underwriters assess flood risk at property level?
Mitigrate combines flood hazard data with property-level vulnerability and prevention measures. This allows underwriters to assess the expected impact of flooding at an individual property and how that risk could change if prevention measures are implemented.
Can flood prevention be assessed across an entire insurance portfolio?
Yes. Mitigrate screens portfolios to identify the properties driving the greatest preventable losses. This helps underwriting teams prioritise where prevention, further assessment or underwriting action can have the greatest impact.
How can prevention be used when pricing flood risk?
Mitigrate models expected losses before and after prevention and estimates the cost and effectiveness of recommended measures. Underwriters can use this information alongside existing risk and pricing data when considering premiums, deductibles and coverage.
How can insurers verify that flood prevention measures have been implemented?
Mitigrate can verify whether recommended measures are in place and document the evidence at property level. This gives underwriters updated information that can be used at renewal or when a property is reassessed.
How does Mitigrate work with existing flood and catastrophe models?
Mitigrate complements existing hazard and catastrophe models rather than replacing them. Existing models show the flood exposure; Mitigrate adds property-level information about vulnerability, prevention measures and how those measures could reduce expected losses.
Take the next step
Know which properties to act on first.
See where prevention could have the greatest impact, and what that could mean for risk selection, pricing and portfolio decisions.